Progressive Leasing can be useful when an essential purchase cannot wait, but the financial outcome hinges on one deadline: the 90-day purchase option. The company’s own help center says its standard agreement runs 12 months and that completing the full schedule can cost more than double the retailer’s cash price, while the 90-day option is the least-expensive lease-to-own path in most states.
That makes the real question less “Is Progressive Leasing good or bad?” and more “Which price are you agreeing to pay?” A shopper looking only at the recurring payment can miss the difference between the retailer’s cash price, the amount needed to own the item within 90 days, and the full 12-month lease-to-own total. Those are three different numbers, and the gap between them can be the difference between paying a manageable premium for immediate access and paying hundreds of dollars more than the item’s sticker price.
This guide treats Progressive Leasing as a cost-control decision rather than a generic financing review. It explains how the lease works, how the 90-day option changes the economics, what current credit-reporting language actually says, how cancellation works, what the FTC settlement means today, and which shoppers are most likely to benefit or overpay. The central rule is simple: if the early-purchase amount is not realistic, evaluate the agreement as an expensive rental path with an ownership option, not as cheap financing.
What Progressive Leasing Actually Is
Progressive Leasing is a lease-to-own provider. Instead of lending the shopper money, Progressive purchases eligible merchandise from a participating retailer and leases that merchandise to the customer. Ownership comes after the required payments are completed or after an early purchase option is exercised.
That legal and economic structure matters. There is no conventional APR to compare with a credit card or personal loan. Instead, the customer should compare total dollars paid. Progressive states that acquiring ownership through the lease costs more than the retailer’s cash price, and its help center warns that the 12-month total could cost more than double the retail cash price.
For the current company explanation, see Progressive Leasing’s lease-to-own basics.
How the Lease Works Step by Step
1. Apply: Progressive reviews multiple data points, including credit-bureau information, income, and banking history. A credit history is not necessarily required, and not every applicant is approved.
2. Choose eligible merchandise: Approval is not a blank check. The item must be eligible and purchased through a participating retailer, within the approved amount.
3. Sign the lease and make the initial payment: Progressive says it does not charge an application or processing fee. The initial payment is the first lease payment and forms part of the 12-month lease total.
4. Receive the item: The lease term and scheduled payment process are tied to receipt of the merchandise. Progressive says scheduled recurring payments do not begin before the customer receives the item.
5. Decide whether to buy early: The customer can use the 90-day option, another early buyout option later in the term, or continue on the standard 12-month schedule.
The 90-Day Purchase Option Is the Cost-Control Lever
Progressive describes the 90-day purchase option, called a three-month option in California, as its least-expensive lease-to-own purchase option. The amount includes the merchandise cash price plus the lease-to-own cost for the first 90 days. Outside California, Progressive also states that the 90-day option still costs more than the retailer’s cash price.
The deadline is based on delivery, not simply the day an application is approved. Progressive’s current help material says the option expires 90 days after the item is delivered. That detail matters for large appliances, furniture, or online orders with delayed delivery.
The three prices to compare before signing
A shopper should ask for these three numbers in writing before treating the payment as affordable:
| Price to compare | What it means | Why it matters |
| Retailer cash price | The normal price if paid outright. | This is the benchmark. Every lease cost should be measured against it. |
| 90-day purchase amount | Cash price plus the lease-to-own cost for the first 90 days. | Usually the lowest-cost ownership route through Progressive. |
| 12-month lease-to-own total | All scheduled lease payments plus lease-to-own cost and applicable tax. | This is the expensive fallback if the lease simply runs its full course. |
A worked example: why the monthly payment can hide the decision
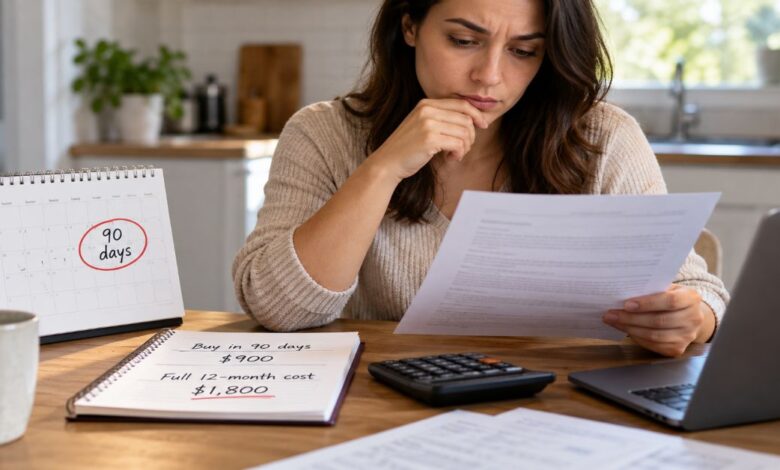
Suppose a laptop has an $800 retailer cash price. The exact Progressive amounts vary by agreement, so the shopper should use the actual disclosure rather than a generic percentage. For illustration only, imagine the 90-day purchase amount is $950 and the 12-month total is $1,500.
The first decision is whether immediate access is worth $150 more than paying cash. The second, much larger decision is whether missing the early window could turn that premium into $700 above cash. Looking only at the recurring payment obscures both questions. Looking at total cost makes them unavoidable.
A useful stress test is to divide the 90-day amount by the number of paychecks expected before the deadline. If the required amount per paycheck is not realistic after rent, food, utilities, transportation, and minimum debt payments, the early option is not a plan; it is an aspiration.
How Much Can the Full 12-Month Path Cost?
Progressive’s current help center says the 12-month lease-to-own total consists of the retail cash price plus the lease-to-own cost for the full term and that this amount could cost more than double the retail cash price. That does not mean every lease doubles the sticker price, but it is a strong reason to compare the disclosed total before signing rather than estimating from one weekly or biweekly payment.
The economic risk is not an interest rate hidden inside a loan. It is a high total cost embedded in a rental-purchase structure. That distinction changes the vocabulary, but not the household-budget impact.
What changes after day 90
Missing the 90-day deadline does not force the customer to remain for the entire 12 months. Progressive says an early buyout remains available later in the term for less than the unpaid 12-month total. The later buyout can still reduce cost, but it is generally less favorable than the initial 90-day option.
Progressive Leasing vs Credit Cards, BNPL, and Rent-to-Own
The closest alternative depends on the shopper’s credit profile and the purchase. The comparison below focuses on structure, not marketing labels.
| Option | Ownership model | Credit impact | Best fit | Main risk |
| Progressive Leasing | Lease now; own through early purchase or completion. | Application should not impact FICO, but lease information may be reported. | Urgent essential purchase with a credible early-payoff plan. | High total cost if the lease runs long. |
| Low-APR credit card | Purchase immediately; repay revolving balance. | Usually reported to bureaus. | Qualified buyers who can repay quickly. | Interest and revolving debt if balance persists. |
| BNPL | Installment purchase, often over a shorter term. | Varies by provider and product. | Smaller purchases with predictable cash flow. | Stacking multiple plans and overextension. |
| Traditional rent-to-own | Rental payments with an ownership option. | Often limited credit-building value. | Consumers excluded from conventional credit. | Total ownership cost can be very high. |
| Saving and paying cash | Immediate ownership at purchase. | No direct credit-building effect. | Non-urgent purchases. | Delay; not viable for urgent replacement needs. |
If a shopper qualifies for genuinely low-cost conventional credit and can repay on schedule, Progressive is usually difficult to justify on price alone. Its value proposition is access and flexibility, not cheap capital.
Does Progressive Leasing Affect Credit?
The most accurate answer in 2026 is nuanced. Progressive says applying for a lease-to-own agreement should not affect a FICO score, although it does review credit-bureau reports and other data. It also says it does not currently report lease-to-own applications to credit bureaus.
However, the company now states that information about the lease may be reported to consumer reporting agencies, and that late payments, missed payments, timely payments, or other defaults may be reflected in a credit report. That means shoppers should not rely on older summaries claiming Progressive never reports payment history.
The current wording appears in Progressive’s credit-reporting FAQ.
Do not use it primarily to build credit
Because Progressive says it is not required to report lease information even upon request, a successful lease is not a dependable credit-building strategy. Someone whose main goal is to establish a positive payment history should compare products designed to report consistently.
Where It Is Available — and Why You Should Verify by ZIP Code
Progressive’s general website currently says the service is not available in Minnesota, New Jersey, or Wisconsin. Some retailer-specific Progressive pages and older advertising disclosures also list Vermont, Wyoming, or Puerto Rico. Because those disclosures are not perfectly consistent, the safest editorial advice is to verify availability for the customer’s ZIP code and retailer immediately before applying.
Retailer participation also changes. Progressive’s shopping pages currently feature large retailers such as Amazon, Apple, Best Buy, Home Depot, Lowe’s, Target, Walmart, Wayfair, and others, but eligible merchandise can vary by store and category.
Use Progressive Leasing Only in These Situations
This product makes the most sense when the purchase solves a real near-term problem and the customer can control the duration of the lease. The strongest use cases are narrow:
| Situation | Why it can make sense | What must be true |
| Essential appliance fails | Waiting may disrupt food storage, laundry, or basic household function. | The 90-day amount fits the next three months of cash flow. |
| Work computer or phone is required | Loss of the device can threaten income. | The item is eligible and replacement cannot reasonably wait. |
| Conventional credit is unavailable | Lease-to-own can provide access without relying on a strong credit score. | The customer understands total cost and has compared alternatives. |
| Cash is expected soon | A tax refund, bonus, or predictable receivable may fund early purchase. | The expected cash is highly likely, not speculative. |
Skip It When the Purchase Is Optional
The weakest use cases are discretionary purchases that create no financial or practical urgency: jewelry, luxury phones, gaming upgrades, décor, or impulse electronics. A high lease premium is hardest to defend when waiting has little downside.
It is also a poor fit when the customer qualifies for low-APR financing, can save for the item within a reasonable period, wants a product specifically to build credit, or cannot explain exactly how the 90-day amount will be funded.
Cancellation and Returns Are a Real Escape Valve
Progressive says customers can cancel a lease at any time and return the merchandise without an additional cancellation charge or penalty. The customer may still owe unpaid lease-to-own costs already accrued. The return process is coordinated through Progressive, which may direct the item back through the retailer or directly to Progressive.
This matters because the decision is not binary between paying the full term and defaulting. If the early purchase plan stops being realistic, contacting Progressive about cancellation or return can prevent future lease payments from continuing to compound the cost.
Progressive’s current returns and cancellation guidance explains the process.
The FTC Settlement: What It Means for Shoppers Today
In April 2020, the Federal Trade Commission alleged that Progressive Leasing misled consumers about the true price of its rent-to-own plans, including through “same as cash” and “no interest” messaging that could lead shoppers to believe they would pay no more than the sticker price. Progressive agreed to pay $175 million to settle the charges and was required to improve cost disclosures and monitor retailer marketing. A stipulated settlement resolves allegations; it is not the same as an admission of wrongdoing.
The refund process continued years later. In June 2021, the FTC announced more than $172 million in refunds to over two million consumers, with an average refund of about $85. In September 2025, the FTC announced a second distribution of more than $27 million in checks to eligible people who had cashed their first checks and met the payment threshold.
Eligibility was tied to the FTC settlement and refund program, not to being a current Progressive customer. The authoritative source is the FTC Progressive Leasing refund page.
The practical lesson from the case
Do not rely on a salesperson’s shorthand. The governing document is the lease disclosure showing the cash price, recurring payments, 90-day purchase amount, and full 12-month total. If the verbal explanation and written agreement do not match, stop before signing.
Questions to Ask Before Signing
- What is the retailer’s cash price for this exact item?
- What is my exact 90-day purchase amount, and what date does that option expire?
- What is the full 12-month lease-to-own total including estimated tax?
- How much must I set aside from each paycheck to finish within 90 days?
- What happens if I miss the 90-day deadline but want to buy out in month four or five?
- Is this specific item eligible, and does the retailer impose any separate return conditions?
- If my income changes, how do I return the item and cancel the lease?
- What information about this lease may be reported to consumer reporting agencies?
The Future of Progressive Leasing in 2027
The clearest direction for lease-to-own is not a dramatic change in the product itself but stronger digital disclosure and tighter cost visibility. Progressive’s current website already places repeated warnings on shopping pages that ownership through leasing costs more than the retailer cash price, while the 2020 FTC order required clearer total-cost presentation and retailer oversight.
In 2027, shoppers should expect the competitive pressure to come from two sides. First, BNPL and alternative-credit products continue to normalize shorter, app-based repayment experiences. Second, regulators remain focused on whether consumers understand total cost before authorizing recurring payments. Lease-to-own providers therefore have an incentive to make early-purchase amounts, delivery-based deadlines, cancellation rules, and total ownership cost easier to see inside mobile checkout.
What is uncertain is whether lease-to-own will become materially cheaper. Its core role remains access for customers who may not qualify for mainstream credit. Unless the pricing structure changes, the strongest consumer strategy will remain the same: shorten the lease duration, compare total dollars rather than periodic payments, and use the return option when ownership stops making financial sense.
Key Takeaways
- The 90-day purchase option is the main cost-control tool; the full 12-month path can be far more expensive.
- Compare three numbers before signing: cash price, 90-day purchase amount, and 12-month lease total.
- The option usually makes the most sense for an urgent essential item, not a discretionary upgrade.
- Applying should not affect FICO, but current company language says lease information may be reported to consumer reporting agencies.
- The 90-day window is tied to delivery, so delayed shipping can matter.
- Cancellation and return can be financially preferable to drifting into a long, expensive lease.
- FTC refund eligibility is historical and program-specific; current customers are not automatically entitled to compensation.
Conclusion
Progressive Leasing is best understood as an access product with an expensive default path, not as a cheap substitute for conventional financing. Its value is highest when an essential purchase cannot wait and the customer has a realistic way to complete the early purchase option. In that narrow scenario, the premium over cash may be a deliberate trade for speed and approval flexibility.
The risk appears when the recurring payment becomes the only number the shopper watches. A small weekly or biweekly draft can make the agreement feel manageable even when the full 12-month total is difficult to justify. The antidote is simple but disciplined: compare total prices, mark the 90-day deadline from delivery, calculate the required amount per paycheck, and decide in advance what happens if that plan fails. If the math does not work before signing, it is unlikely to improve after the lease begins.
FAQ
Can I use Progressive Leasing without a bank account?
Progressive’s application and payment setup relies on approved payment methods and banking information as part of its evaluation. Exact requirements can vary, so applicants should confirm the accepted payment methods during the application rather than assume a prepaid card or cash-only setup will qualify.
Does the Progressive Leasing 90-day option start on purchase day or delivery day?
Progressive’s current help center says the 90-day purchase option expires 90 days after the merchandise is delivered. That makes the delivery date important for online orders, furniture, appliances, or anything with delayed fulfillment.
Do I have to call to use the Progressive Leasing early buyout?
Progressive says customers must contact the company to exercise the 90-day option or other early purchase arrangements. A one-time online payment may be available after arrangements are set, but shoppers should not assume the early option activates automatically.
Can I return an item after using it for several months?
Progressive says a customer can cancel the lease and return the merchandise at any time. The company evaluates the return route, and unpaid lease-to-own costs already accrued may still be owed.
Does approval mean I can lease anything at the store?
No. Approval provides a leasing amount, but the merchandise must be eligible and purchased from a participating retailer. Some categories or items may be excluded even when the customer has unused approval.
Is “no credit needed” the same as “no credit check”?
No. Progressive says a strong credit history is not required, but it does obtain credit-bureau information and considers other data such as income and banking history. “No credit needed” should not be read as “no bureau information is reviewed.”
Does Progressive Leasing build credit?
It is not a dependable credit-building tool. Progressive says it does not currently report lease-to-own applications and is not required to report lease information even on request, although lease activity may be reported to consumer reporting agencies.
Methodology
This article was built from a review of current Progressive Leasing help-center pages, current company shopping and disclosure pages, Federal Trade Commission enforcement and refund material, and a SERP review of leading third-party explainers and review pages. Primary sources were used for product terms, cost disclosures, credit-reporting language, cancellation rules, and the FTC history.
Known limitations: Progressive’s state-availability disclosures are not perfectly consistent across its general website, retailer-specific pages, and older advertising material. Retailer participation and eligible merchandise also change. Readers should therefore verify ZIP-code availability, item eligibility, and the exact lease disclosure at checkout. No relevant live fishaudios.com article URLs were verified through web search, so internal links were not forced into unrelated content; internal linking should expand as the site publishes closely related finance guides.
Balanced perspective: lease-to-own can provide meaningful access when conventional credit is unavailable, especially for urgent essential purchases. That utility does not erase the high total-cost risk when the agreement remains open for the full term.
This article was drafted with AI assistance and reviewed by a human editor before publishing. All data, citations, and claims have been independently verified against primary sources.
References
- Federal Trade Commission. (2020, April 20). Rent-to-own payment plan company Progressive Leasing will pay $175 million to settle FTC charges it deceived consumers about pricing.
- Federal Trade Commission. (2025, September). Progressive Leasing refunds.
- Progressive Leasing. (2025, May 16). What are my early purchase options?
- Progressive Leasing. (2026, April 15). Does Progressive report to credit bureaus? Can I build up my credit by doing a successful lease?
- Progressive Leasing. (2024, October 24). Are returns allowed?
- Progressive Leasing. (2024, October 22). How does Progressive Leasing calculate my remaining 12 month lease-to-own total?